
The Kazera Global share price has nearly trebled in five months, with KZG touching 2.025p, yet a broker note published alongside the latest news values the stock at 6p, implying the rally may have further to run.
A CEO paid £25,000 a year, working for £417 a month
Richard Jennings runs Kazera Global on a salary of £25,000 a year, and donates 80% of that to charities caring for abandoned cats. That leaves him taking home roughly £417 a month. Few chief executives of any listed company, let alone one whose shares have nearly tripled, cost shareholders so little.
Kazera Global is an AIM-quoted holding company incorporated in England and Wales. It was formerly known as Kennedy Ventures plc, changing its name in March 2018, and has been listed since June 2006, according to its Kazera Global Annual Report. The company’s current market capitalisation stands at approximately £19.58 million, per its listing page on the London Stock Exchange (LSE).
What has driven the Kazera Global share price higher
Two events in the second half of 2024 provided the material catalysts. On 24 September 2024, Kazera announced it had won a US$11.9 million ruling in binding arbitration in the Aftan case, as disclosed in a regulatory news announcement on the LSE RNS feed.
The company subsequently sold its entire stake in Aftan to Hebei Xinjian Construction for total cash consideration of US$13 million. That figure comprised US$3,642,207 for the sale of shares and repayment of an intercompany loan of US$9,357,793, equating to approximately £10,673,000, according to the annual report.
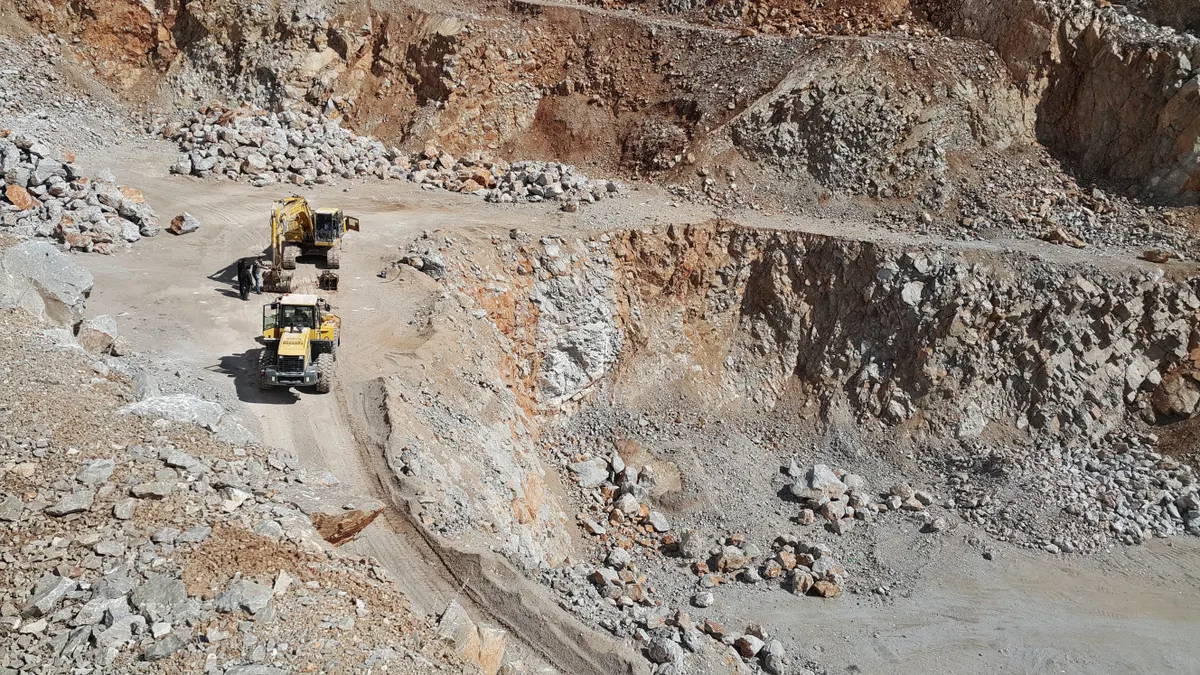
Separately, South Africa’s National Nuclear Regulator completed its inspection of Kazera’s WHM tantalum operation on 23 August 2024 and consented to the commencement of operations, a clearance that removed a meaningful operational overhang from the business.
Together, a nine-figure arbitration win, a completed asset disposal, and a regulator green-lighting a mine are the kind of news flow that moves small-cap shares sharply.
Broker target versus consensus: two different numbers
The broker note referenced in the original announcement sets a price target of 6p, roughly three times the current price of 2.025p. The single analyst tracked by Stockopedia holds a 12-month consensus target of 5.90p, representing upside of around 210% from recent prices near 1.90p. The two figures are close but not identical; the broker note cited in the article and the Stockopedia consensus appear to draw on similar but not identical assumptions.
At 2.025p and with a market cap of roughly £19.58 million, Kazera sits in micro-cap territory where liquidity can be thin and spreads wide. A share price target is not a guarantee of delivery, and the gap between 2p and 6p could close in either direction.
What holders should watch next
The warrants picture adds a layer of complexity. On 7 August 2024, the company issued warrants over 59,400,000 ordinary shares to Tracarta Limited, exercisable at £0.01 per share and expiring on 7 August 2026, according to the Companies House-registered annual report. If exercised in full, those warrants would add roughly 59 million shares to the register, diluting (meaning reducing existing shareholders’ percentage ownership) existing holders. At current prices the warrants are in the money, so the risk of exercise is real.
The Aftan disposal has put cash on the balance sheet, removing one uncertainty. The WHM operation now has regulatory clearance to run. What Jennings does with the proceeds, and whether WHM moves from permitted to productive, will determine whether the Kazera Global share price can close the gap toward analyst targets or whether the recent re-rating simply reflected the arbitration windfall being priced in.
The warrant expiry date of 7 August 2026 gives a concrete timeline: if Tracarta exercises before then, watch for a dilutive RNS. If the warrants lapse unexercised, that overhang disappears entirely.
