
Investors in Victoria plc (VCP) saw the Victoria plc share price slide more than 3% to 56p on 3 September 2026, even as the company issued an upbeat AGM statement describing an encouraging start to its financial year.
The contrast is hard to ignore. Management said the UK business ‘continues to perform strongly’ and that the group ‘will assess any opportunities that may consequently arise’ from the collapse of Headlam Group. Markets, for now, are not convinced.
What the AGM Statement Did and Did Not Say
Victoria’s AGM Statement on the London Stock Exchange offered encouragement on trading, but it also contained a passage that deserves closer attention: the company confirmed that good progress is being made on refinancing its 2028 bonds and preferred equity (shares ranking above ordinary shares for dividends and capital), and that this process ‘remains on track for completion.’
The refinancing of debt maturing in 2028 is not an immediate crisis, but it is a live process. Bond markets watch refinancing timelines carefully, and until that work is formally completed, it remains an open item on the balance sheet.
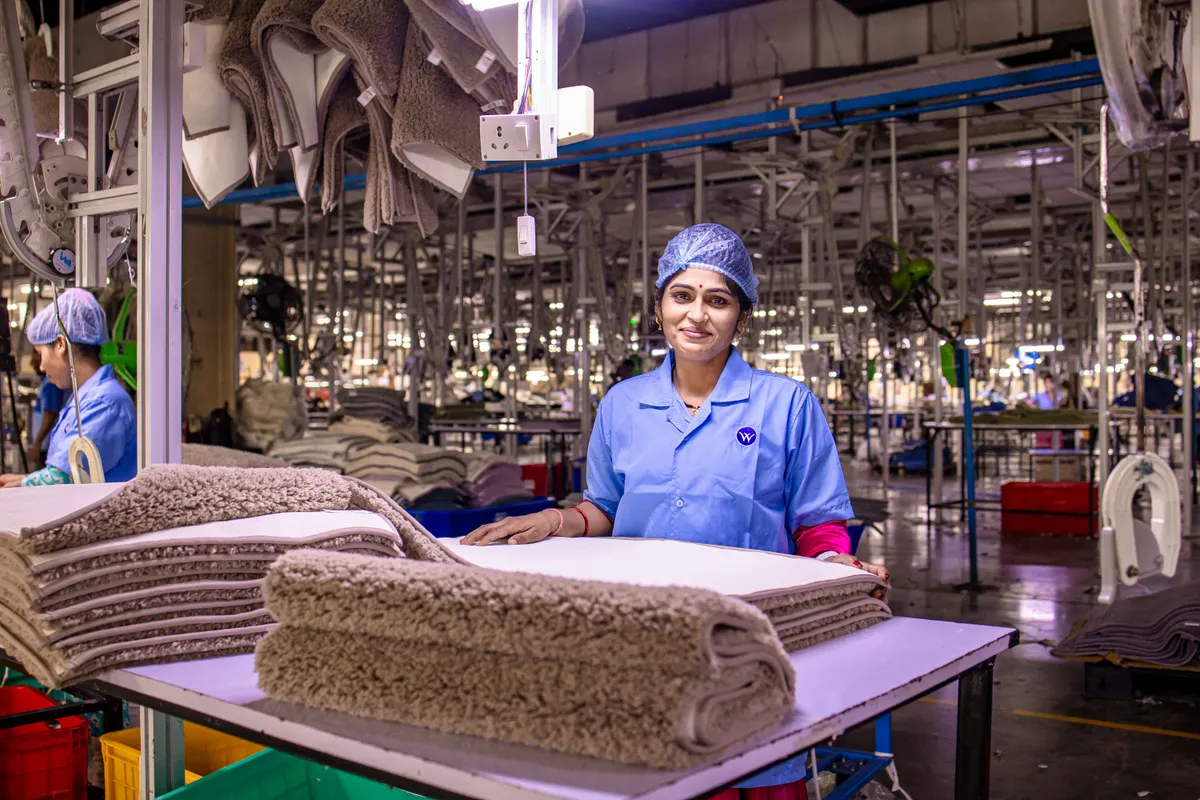
Victoria plc is Europe’s largest carpet manufacturer and the largest manufacturer of underlay in both Europe and Australia. It employs approximately 6,300 people across more than 30 sites spanning the UK, Spain, Italy, Belgium, the Netherlands, Germany, Turkey, the USA and Australia. The company was established in 1895 and has traded on AIM (the London Stock Exchange’s market for smaller companies) since 2013 under the ticker VCP.
Victoria plc Share Price and the Headlam Factor
Headlam Group, which described itself as the UK’s leading floor coverings distributor with over 30 years of operation and a nationwide delivery network, filed a notice of intention to appoint administrators on 31 August 2026, stating that administrators would be appointed within five business days.
The trigger was the exhaustion of liquidity under Headlam’s £85 million asset-based lending facility (a revolving credit line secured against stock and receivables), according to Kalkine’s analysis of the administration filing.
Administrators were duly appointed. Will Wright, Chris Pole and Ryan Grant of Interpath Advisory took formal control of Headlam Group plc and its subsidiary HFD Limited, with the existing management team remaining in place under their direction and supervision, according to the Headlam administrator appointment announcement on the London Stock Exchange. Stephen Bird, Non-Executive Chairman, and Nick Kelsall, independent Non-Executive Director and Audit Committee Chair, both stepped down from the board upon the appointment.
For Victoria, Headlam’s failure removes the UK’s dominant distributor of floor coverings from the market. Victoria sells through distributors as well as directly, so an opening in the distribution landscape is a genuine opportunity. Management’s careful phrasing, ‘will assess any opportunities that may consequently arise,’ is the corporate equivalent of saying the door is open without committing to walking through it.
The question for investors is whether Headlam’s collapse represents a market share gain waiting to happen or a sign that conditions across the whole floor coverings sector are deteriorating fast enough to drag on everyone in the chain, Victoria included. A distributor running out of headroom on an £85 million facility suggests demand weakness, margin pressure, or both, and those same forces affect manufacturers upstream.
The Headlam trading update on Investegate had already flagged a difficult trading environment in the months before administration.
At 56p, VCP shares sit in territory that reflects considerable scepticism about near-term recovery. The refinancing of the 2028 bonds is management’s clearest near-term milestone: completion would remove one source of uncertainty and potentially give the Victoria plc share price firmer ground to stand on. Until then, the AGM’s encouraging tone and the market’s 3% sell-off are both pointing at the same question, just from different directions.
