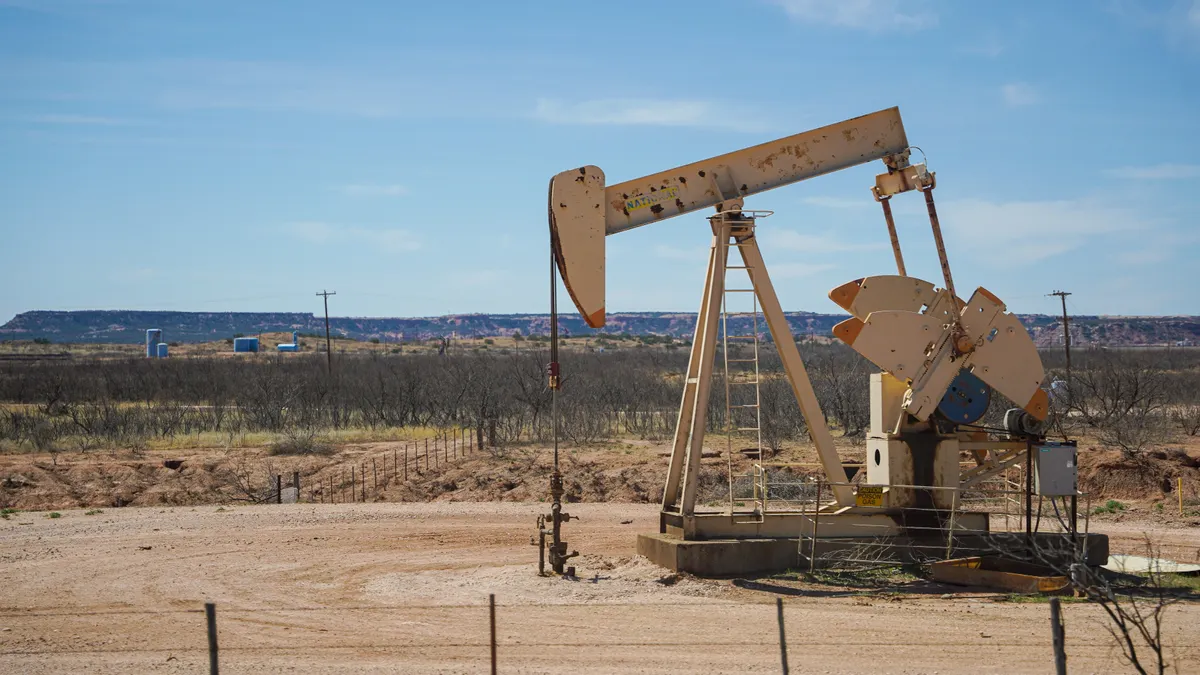

The Union Jack Oil offer from Reabold Resources has moved into a critical phase, with two further AIM special situations, Jarvis Securities and Sutton Harbour Group, also attracting attention from investors looking for corporate event-driven returns.
The Union Jack Oil Offer: What Holders Need to Know
Reabold Resources put forward a non-binding and indicative all-share proposal (a preliminary, non-committed approach) for the entire issued share capital of Union Jack Oil (UJO). Under the UK Takeover Code, Reabold faced a deadline of 13 July 2026 to either announce a firm intention to make an offer or walk away.
It did not walk away. A Recommended All Share Offer was announced on 1 July 2026, with a formal Offer Document published on 28 July 2026, per the London Stock Exchange regulatory news service.
The timetable has since been updated. According to Union Jack Oil’s own offer timetable document, ‘Day 60’ of the offer has been re-set to 2 October 2026, and ‘Day 46’ to 18 September 2026. In Takeover Code parlance, Day 60 is the final deadline by which the offer must either lapse or become unconditional, so this date concentrates the mind.
UJO shares last closed at 3.10p, which sits 55.00% above the 52-week low of 2.00p recorded on 29 December 2025, per FT Markets data. The all-share nature of the deal means UJO holders will receive Reabold shares rather than cash, so the value they ultimately receive depends on where Reabold trades when the offer completes.
UJO describes itself as a production, development and exploration company. Its balance sheet carries no debt, but it has negative earnings and pays no dividend, which limits the valuation floor if the deal were to fall apart. Holders should weigh both sides of that equation before the October deadline.
Jarvis Securities and Sutton Harbour: Two More Corporate Crossroads
Jarvis Securities (JIM) has been providing retail and outsourced financial services since 1984. Its AIM listing now comes with a corporate twist: the company has announced a conditional sale of its retail brokerage business for up to £11 million, per Investing.com. Alongside that, Jarvis changed its financial year end from 31 December to 30 June, a move that tends to complicate year-on-year comparisons for investors tracking progress.
The audited results were delayed into July 2025 and the accounts release date was extended to 30 June 2025, adding a layer of administrative complexity that retail holders need to factor in when assessing the stock. A conditional sale (one subject to shareholder or regulatory approval before completion) of £11 million is not enormous, but for a company of JIM’s size it represents a material restructuring of the business.
The question for any JIM holder is straightforward: what does the business look like after the brokerage arm is sold, and does the remaining entity justify a continued listing?
Sutton Harbour Group (SUH) presents a different kind of decision. The company announced a strategic review and a proposed cancellation of its ordinary shares’ admission to trading on AIM on 28 August 2026. A circular and notice of general meeting followed on 2 September 2026, per the Sutton Harbour Group investor relations page.
An AIM cancellation (delisting from the market) would leave shareholders holding shares in a company with no public market on which to sell them. That is a binary risk. SUH shares closed at 2.50p, a price that sits 150.00% above the 52-week low of 1.00p set on 1 September 2026, per Investors’ Chronicle market data. A property portfolio valuation update and asset sale announcement was published on 3 June 2026, which may inform the net asset backing behind that share price.
The general meeting triggered by the cancellation notice is where holders exercise their voice. Missing that vote, or failing to read the circular, means accepting whatever the majority decides.
All three situations share one feature: a hard corporate deadline approaching. For UJO, it is 2 October 2026. For JIM and SUH, the general meetings and regulatory processes have their own timetables. In each case, the window for holders to act, or at least to form a view, is narrow and closing.
